ProShares' $17.8B Stablecoin ETF (IQMM): Who Keeps the 3.84% Yield on Your Digital Dollars?
ProShares' IQMM now holds $17.81B of stablecoin-linked Treasury assets paying 3.84% — yet stablecoin holders get $0 of that yield. Here's who pockets it, and the 5 checks before you hold digital dollars.
ProShares' GENIUS Money Market ETF, ticker IQMM, now holds $17.81 billion in assets paying a 3.84% seven-day SEC yield — and the people whose dollars fund it get exactly $0 of that yield. That single fact explains the biggest money fight in crypto right now: who keeps the interest on your digital dollars?
The fund, launched in February 2026, is built for one customer above all others: stablecoin issuers parking the reserves behind tokens like USDT and USDC. Under the GENIUS Act, those reserves must sit in cash and short-term US Treasuries — exactly what IQMM holds. Wall Street has noticed. Franklin Templeton has retooled institutional funds for the same market, BlackRock restructured a Treasury liquidity fund for it, and ProShares is now collecting an estimated $26.7 million a year in management fees on its $17.81 billion pile alone. This article breaks down how the machine works, who profits at each step, the redemption risk nobody advertises, and the five checks stablecoin holders should run before trusting any digital dollar.
What IQMM Actually Is — and Why It Exists
IQMM is not a crypto fund in the way most readers imagine. It holds no Bitcoin, no Ethereum, and no stablecoins. It holds cash and short-term US Treasury securities, each maturing in 93 days or less, with a weighted average maturity of about 45 days. As of November 2, ProShares reported 100% daily and weekly liquid assets — meaning the fund can, in theory, hand money back fast.
What makes it different from an ordinary money market fund is its plumbing. Unlike traditional money market funds, IQMM trades on an exchange, calculates its net asset value twice a day, and offers same-day settlement. For a stablecoin issuer managing billions of redeemable tokens, that speed matters: when holders redeem tokens for dollars, the issuer needs cash the same day, not next week.
The fund's structure maps directly onto the GENIUS Act's reserve rules. The Act, signed in July 2025, requires payment stablecoin issuers to back tokens with qualifying reserves — cash and short-term Treasuries — and IQMM is designed so qualifying issuers can hold it as part of those backing assets. In plain terms: the law created a multi-hundred-billion-dollar parking lot for Treasuries, and ProShares built one of the first purpose-built garages. Readers who want the full rulebook should start with our guide to how the GENIUS Act's stablecoin rules work, including the two deadlines that matter most for holders.
The $17.81 Billion Number, Explained
As of early November 2026, IQMM held approximately $17.81 billion in assets, with a seven-day SEC yield of 3.84% and a net expense ratio of 0.15%. Those three numbers tell three different stories.
First, the size. $17.81 billion makes IQMM one of the largest single products ever built explicitly around stablecoin reserves — and it got there in about nine months, from a February 2026 launch. That speed is the market's verdict on the GENIUS Act: regulated stablecoin reserves are now a mainstream Wall Street business, not a crypto niche.
Second, the yield. 3.84% is roughly what short-term US Treasuries pay in late 2026. It is real money: on $17.81 billion, a 3.84% annual yield represents roughly $684 million a year in gross interest before fees and expenses. That interest flows to the fund's shareholders — the institutions holding IQMM shares — not to the retail holders of the stablecoins those reserves back.
Third, the fee. At a 0.15% net expense ratio, ProShares collects roughly $26.7 million a year on current assets, before any change in assets or fees. That is the asset manager's cut for running what is essentially a Treasury parking service. It is small in percentage terms and enormous in absolute terms — and it is only one layer of the fee stack, as the next section shows.
Who Actually Profits From the Treasury Trade
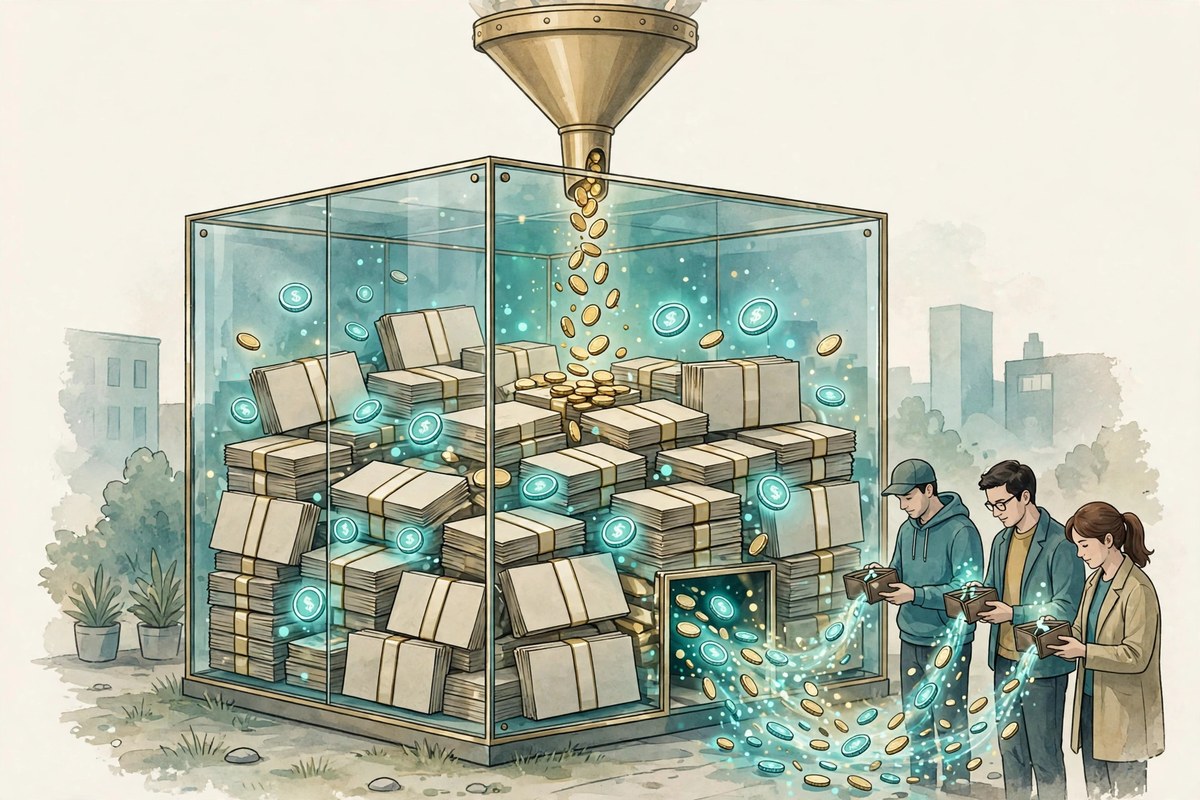
Follow a dollar through the system and the money splits four ways — with the stablecoin holder, the person who supplied the dollar, last in line.
Step one: you exchange $100 for 100 digital dollars. You hold tokens designed to stay at $1. You earn nothing for holding them — the GENIUS Act bars issuers from paying interest or yield on payment stablecoins directly, which is why the separate fight over whether USDC and USDT can pay interest at all matters so much.
Step two: the issuer invests your $100 in qualifying reserves — Treasuries, cash, or funds like IQMM. Those reserves earn roughly the Treasury rate, currently near 3.84% on IQMM's portfolio.
Step three: the issuer keeps the reserve income. Circle, the issuer behind USDC, illustrates the scale: its reserve income reached $667.7 million in the second quarter of 2026 alone, representing more than 95% of its revenue. That is not a side business. Reserve income is the business.
Step four: the asset managers take their cut. ProShares' 0.15% fee on IQMM, Franklin Templeton's fund fees, BlackRock's liquidity-fund fees — each layer shaves a slice before the remainder lands with the issuer. Custody providers, distribution partners, and operating costs absorb more still. Revenue, as the fund documents quietly note, does not equal profit — but the direction of travel is clear: everyone in the chain gets paid except the holder.
This is not a scandal. It is the business model, disclosed in fund documents and earnings reports. But it is the single most misunderstood fact in stablecoins: when you hold a digital dollar, you are lending your money interest-free to a chain of companies that invest it at ~4%.
ProShares vs Franklin Templeton vs BlackRock: The Treasury Race
The competition for stablecoin reserve assets is now a three-way Wall Street race, and each player is pitching a slightly different product.
| Player | Product pitch | What we know |
|---|---|---|
| ProShares (IQMM) | Exchange-traded, twice-daily NAV, same-day settlement, built for GENIUS Act reserves | ~$17.81B assets, 3.84% seven-day SEC yield (Nov 2), 0.15% expense ratio, ~45-day average maturity |
| Franklin Templeton | Modified institutional funds adapted for regulated stablecoin reserves | Repositioned existing institutional money funds for the same reserve market |
| BlackRock | Restructured Treasury liquidity fund targeting stablecoin reserve demand | Moved an existing Treasury liquidity product toward the same institutional customer |
ProShares' edge is that IQMM was purpose-built: exchange trading and same-day settlement suit issuers who may need to liquidate reserves on redemption surges. Franklin Templeton and BlackRock counter with scale and existing institutional relationships — the world's largest asset manager does not need to explain who it is to a stablecoin issuer's board. The winner will likely be decided not by yield — all three hold near-identical Treasuries — but by settlement speed, liquidity terms, and which fund issuers trust in a redemption storm.
For context on which tokens sit behind these reserves, see our comparison of the best stablecoins in 2026 — USDT vs USDC vs DAI — and our beginner's guide to what a stablecoin actually is and how to judge whether one is safe.
What Most People Get Wrong About Stablecoin Yield
Myth one: "My stablecoin earns yield because Treasuries pay interest." Wrong. The Treasuries pay interest to whoever owns them — the issuer or the fund shareholder. Your token is a claim on $1, not a share of the reserve portfolio. Unless you hold the stablecoin through a separate rewards or lending program — which the GENIUS Act restricts — you earn nothing.
Myth two: "A $17.8 billion fund means stablecoins are safer now." Partly wrong. IQMM's size shows the reserve market is maturing, but the fund itself carries risks the marketing skips: it does not promise a fixed $100 share price, and it provides no FDIC deposit insurance. A money market ETF can, in stressed markets, trade below its target value.
Myth three: "If everyone redeems at once, Treasuries are Treasuries — selling is easy." This is the dangerous one. ProShares itself acknowledges that stablecoin issuers may become the fund's largest shareholders, creating concentrated redemption risk. If holders redeem stablecoins en masse, issuers could dump large IQMM positions simultaneously to raise cash. That pressure could hit the fund's liquidity, yield, and share price — even though the underlying holdings are short-term government securities. The assets are safe; the exit door is narrow.
Myth four: "Regulation fixed stablecoins, so all stablecoins are now equal." Wrong. The GENIUS Act sets reserve and licensing rules, but issuers differ in transparency, reserve composition, and redemption history. A token backed by Treasuries held through a regulated fund is a different risk from a token backed by opaque commercial paper or affiliated loans — and the law's January 2027 deadlines will separate the two groups further.
The Redemption Risk Nobody Advertises
The scenario worth understanding is not a Treasury default — that is close to unthinkable — but a liquidity crunch. Imagine a market shock: a major exchange hack, a bank failure, or a rumor about an issuer. Holders rush to redeem stablecoins for dollars. Issuers sell IQMM shares to raise cash. If several large issuers sell at once, the fund faces concentrated outflows that test its same-day settlement promise.
ProShares' defenses are real: 100% daily and weekly liquid assets, 45-day average maturity, and holdings limited to 93-day paper. Those are strong buffers. But buffers are not guarantees, and the fund's own disclosure — no fixed share price, no FDIC insurance — is the honest version of the risk. Holders should treat stablecoins as payment tools and short-term parking, not as bank deposits, and size their holdings accordingly.
This risk connects directly to the week's other big story: Binance customers withdrew a net $4.72 billion after the exchange's $6.3 billion hack, a reminder that redemption surges are not theoretical. They happened, days ago, at the world's largest exchange. Any product built on the assumption that redemptions stay orderly deserves skepticism.
5 Checks Before You Hold Any Stablecoin
Use this checklist before keeping meaningful money in any digital dollar:
- Read the reserve disclosure. Does the issuer publish what backs each token — Treasuries, cash, or something vaguer? Monthly attestations beat annual promises; audited reserves beat self-reported ones.
- Check the GENIUS Act status. Is the issuer licensed or registered under the new framework, and does it meet the January 2027 deadlines? Unlicensed issuers face a different legal future.
- Ask who earns the yield — and whether you get any of it. If the answer is "the issuer keeps it," that is normal — but then judge the token on safety and redemption speed, not on any implied return.
- Test a small redemption. Redeem a small amount for dollars before you trust a token with a large amount. Speed and friction in calm markets predict behavior in a crisis.
- Size it like cash, not like savings. No FDIC insurance, no fixed share price on reserve funds, no interest. Hold what you need for payments and trading — not your emergency fund.
What Happens Next: 3 Scenarios for the Treasury Race
Bull case for IQMM-style funds: stablecoin supply keeps growing under GENIUS Act licensing, issuers standardize on exchange-traded reserve funds, and IQMM doubles toward $35 billion by mid-2027, pulling Franklin Templeton and BlackRock into a fee war that benefits issuers.
Base case: growth continues but slows as the January 2027 deadlines force weaker issuers out, concentrating reserves among a few large issuers — which ironically increases the concentrated-redemption risk ProShares discloses.
Bear case: a redemption shock or a regulatory challenge to reserve-fund structures forces issuers to hold reserves directly in Treasuries rather than through funds, shrinking IQMM and handing the business back to custodian banks.
Whichever path plays out, the structural fact remains: as long as stablecoins pay holders $0 and Treasuries pay ~4%, there is a multi-billion-dollar spread up for grabs — and Wall Street's biggest firms are now fighting over it in public.
FAQs
What is ProShares' IQMM ETF?
IQMM is the ProShares GENIUS Money Market ETF, an exchange-traded fund holding cash and short-term US Treasury securities (maturities of 93 days or less). Launched in February 2026, it is designed so stablecoin issuers can hold it as part of their GENIUS Act-compliant reserves. As of early November 2026 it held about $17.81 billion, with a 3.84% seven-day SEC yield and a 0.15% expense ratio.
Do stablecoin holders earn the IQMM yield?
No. The yield goes to the fund's shareholders — the institutions holding IQMM shares, typically the stablecoin issuers themselves. Retail stablecoin holders receive tokens pegged to $1 and earn no interest from the reserve portfolio, and the GENIUS Act restricts issuers from paying yield directly on payment stablecoins.
Is IQMM FDIC insured?
No. ProShares states the fund does not promise a fixed $100 share price and provides no FDIC deposit insurance. It is an investment product holding government securities, not a bank deposit.
Why are Franklin Templeton and BlackRock competing here?
Because stablecoin reserves are now a huge, fast-growing pool of Treasury demand. Issuers must park hundreds of billions of dollars in qualifying assets, and asset managers earn recurring fees for running those portfolios — ProShares alone collects an estimated $26.7 million a year at current assets and fees.
What is the biggest risk to IQMM?
Concentrated redemptions. If stablecoin issuers become the fund's largest shareholders and all redeem at once during a crisis, large simultaneous sales could pressure the fund's liquidity, yield, and share price, even though its holdings are short-term government securities.
Should I buy IQMM instead of holding stablecoins?
They serve different purposes. IQMM is an institutional money market product for reserve managers; stablecoins are payment and trading tools for crypto users. Retail investors should not treat either as a bank account, and should check with a financial adviser before investing. Nothing here is financial advice.
Conclusion
The $17.81 billion sitting in ProShares' IQMM is the clearest proof yet that stablecoins grew up: the wild west of crypto dollars is now a Treasury management business fought over by Wall Street's biggest names. The yield is real — 3.84% on tens of billions — but it flows to issuers and asset managers, not to the holders who supplied the dollars. That is legal, disclosed, and, for now, the deal on offer. Holders who understand it can use stablecoins wisely: as fast payment rails and short-term parking, sized like cash, chosen on transparency and redemption speed rather than any promised return. The firms that keep the spread will keep competing for it — and the next chapter of that fight, through the GENIUS Act's January 2027 deadlines, will decide whether the spread narrows, widens, or gets shared. Watch the reserves, not the marketing.
Sources: ProShares GENIUS Money Market ETF (IQMM) holdings, yield and fee data as reported by KuCoin News; Circle Q2 2026 reserve income of $667.7 million as reported in the same coverage; GENIUS Act reserve framework context from the SEC's expanded crypto token FAQ coverage and the CLARITY Act status report. Figures are as reported in early November 2026 and may change.