Crypto Tax in 2027: The IRS Already Has Your Trades — 5 Dates That Decide What You Owe
The first 1099-DA forms already reached roughly 9 million Coinbase users — and in 2027 the IRS gets your cost basis too. Five deadlines decide what you owe, and the move that saves you the most money has to happen before December 31.
The IRS already has your crypto trades. In January 2026, roughly 9 million Coinbase customers received the first-ever Form 1099-DA, a federal tax form documenting their digital-asset sales. In early 2027, the second wave lands — and this time it carries your cost basis too. Meanwhile, 47 countries start swapping crypto transaction data with each other in 2027, and Bitcoin sits 41% below its all-time high, which means millions of holders are sitting on losses they can still use — but only if they act before December 31, 2026.
2027 is the year crypto tax stops being something you figure out in April and becomes something your exchange reports for you. Here are the five dates that decide what you owe, the traps the new forms create, and the five moves to make before the year ends.
The 5 Dates That Decide Your 2027 Crypto Tax Bill
Crypto tax in 2027 comes down to five deadlines. Miss one and you pay more, or get flagged by an automated system that now has your data.
| Date | What happens | Who it hits |
|---|---|---|
| December 31, 2026 | Last day to harvest 2026 tax losses and lock in your cost-basis method for the year | Every holder with unrealized losses |
| January 18, 2027 | GENIUS Act stablecoin rules take effect in the US | Stablecoin holders and issuers |
| February 15, 2027 | Brokers must send you your 1099-DA for 2026 sales — now including cost basis for covered assets | US exchange users |
| May 31, 2027 | UK crypto providers file their first CARF reports with HMRC, covering all of 2026 | UK residents on reporting platforms |
| September 30, 2027 | EU countries exchange their first DAC8 crypto reports with each other | EU residents on any EU platform |
The forms your exchange sent you in early 2026 only showed gross proceeds — the total dollars from your sales, with no mention of what you paid. The forms arriving in early 2027 are different. For any coin you bought on or after January 1, 2026 and kept on the same exchange until you sold it, the IRS will now see what you paid, what you received, and the gain or loss in between. That is the whole game changing in one form.
What Form 1099-DA Actually Reports — and What It Gets Wrong
Form 1099-DA, Digital Asset Proceeds From Broker Transactions, is the crypto version of the 1099-B that has reported stock sales for decades. It was created by the Infrastructure Investment and Jobs Act of 2021, detailed in Treasury's final regulations of July 2024, and the first wave covered sales made in 2025. The phased rollout is where most holders get tripped up:
- 2025 sales (reported in early 2026): gross proceeds only. No cost basis, no holding period. The IRS could see you sold $50,000 of crypto but not whether you made or lost money.
- 2026 sales (reported in early 2027): gross proceeds plus cost basis — but only for "covered" assets, meaning coins bought on or after January 1, 2026 and held in the same custodial account until sale.
- Everything else is "noncovered": any coin bought before 2026, and any coin moved in from another platform or a wallet you control, is noncovered forever. Your broker has no obligation to report its basis — and may report a wrong one.
That last point is the trap. If you transferred Bitcoin from your own wallet to Coinbase and sold it, Coinbase may show the transfer-in date as your acquisition date, or report zero basis. The IRS regulations are explicit that you are not required to use the transfer date as your acquisition date — your real purchase date and real cost govern — but you have to prove it on Form 8949 with your own records. If you do nothing and the IRS's automated matching program sees proceeds with no offsetting basis, it can treat the entire sale as gain. That is how a $10,000 sale of coins you bought for $9,500 becomes a $10,000 "gain" in the machine's eyes unless your return says otherwise. For the full mechanics of the US rules, see our guide to crypto tax in the USA in 2026.
Decentralized finance was carved out: in April 2025, Congress repealed the rule that would have made DeFi protocols and decentralized exchanges file 1099-DAs. The gains are still taxable — only the automatic form is missing, so the record-keeping burden falls entirely on you.
The Cost-Basis Trap: Why Your Exchange's Number Will Be Wrong
Since January 1, 2025, the IRS requires cost basis to be tracked wallet by wallet, account by account. The old approach of pooling all your Bitcoin across every exchange and wallet into one average cost is gone. Each wallet and each exchange account is now its own basis silo, and the method you use to identify which coins you sold — first-in-first-out, specific identification, or another permitted method — must be set before the sale, not after it. Starting in 2027, your broker must have your basis-identification instruction no later than the sale itself, or its default order applies.
The practical problem for 2027: if you bought the same coin on three exchanges, sold some on one of them, and never told the broker which lots to use, the broker's default may not match your records — and the mismatch is exactly what the IRS's Automated Underreporter system is built to catch. In 2026, matching was lumpy because basis was missing from the forms. For 2026 transactions reported in 2027, matching gets sharper: the IRS will have proceeds and, for covered tokens, basis. Mismatches become CP2000 notices, the automated letters that propose extra tax plus interest.
DAC8 and CARF: Europe and the UK Join the Dragnet in 2027
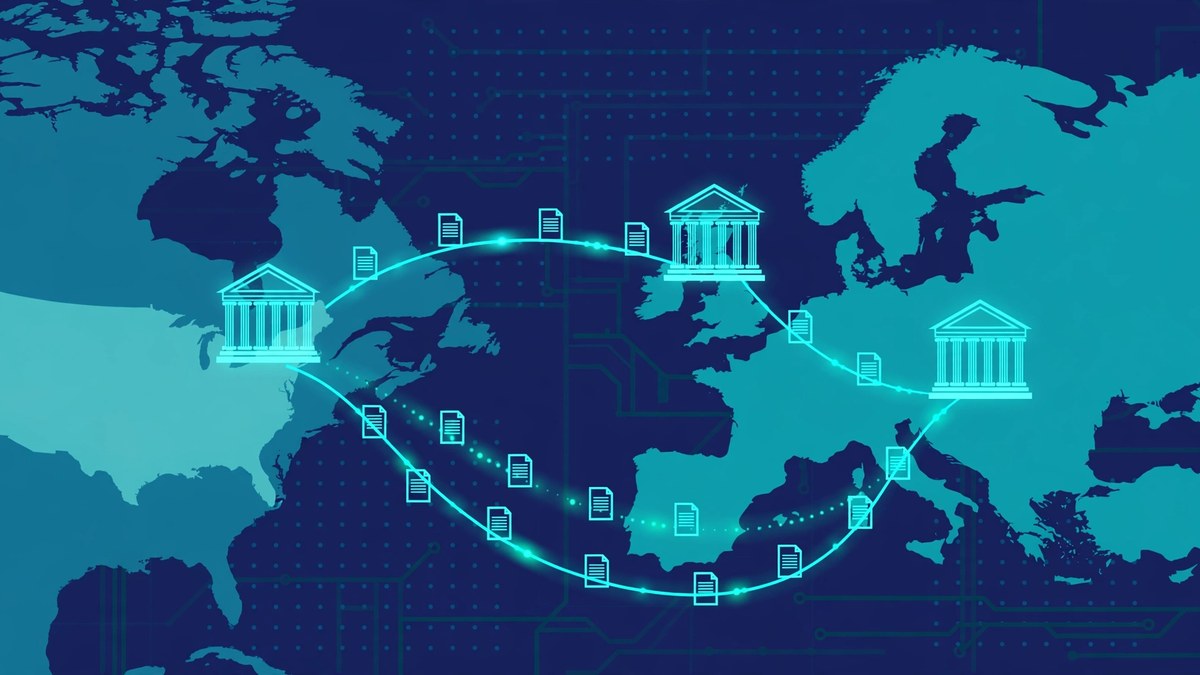
While the US tightens its own reporting, the rest of the world is wiring up a cross-border version of the same machine. The OECD's Crypto-Asset Reporting Framework (CARF) and the EU's DAC8 directive both started applying on January 1, 2026. The first reports and exchanges of information take place in 2027 — and the scale is large: 47 jurisdictions are targeting their first CARF exchanges in 2027, and 83 jurisdictions had signed the framework as of October 1, 2026.
Under DAC8, EU crypto providers must collect your name, address, tax ID and a summary of your transactions, then report them to their home tax authority. The first intra-EU exchanges of that data are due by September 30, 2027, covering 2026. The UK implemented CARF in parallel: UK providers must file their first reports with HMRC by May 31, 2027, and the UK version also covers domestic activity by UK residents, not just cross-border holdings. Under DAC8, a provider that does not receive your tax ID must stop executing transactions and can freeze withdrawals.
Two things about these reports surprise most holders. First, they do not calculate your tax. They report gross proceeds, unit counts and transaction categories; working out the gain or loss is still your job. Second, they can be incomplete in ways that hurt you: a report covers one provider, not your whole portfolio, so a loss on one exchange never appears next to a gain on another unless you put them together on your return. For the wider regulatory picture, including the US GENIUS Act deadline of January 18, 2027 and the CLARITY Act's January 3 expiry, see our breakdown of crypto regulation in 2027.
The 24% Backup Withholding Rule Nobody Is Talking About
Buried in the 1099-DA phase-in is a rule that can take money out of your account before you ever file a return. From 2027, backup withholding can apply at 24% if your broker does not have a certified taxpayer identification number for you. The penalty relief and withholding waivers that covered 2025 and 2026 sales do not extend into 2027 in the same way. In practice, an unverified account selling crypto in 2027 can have nearly a quarter of the proceeds withheld and sent to the IRS. It is recoverable when you file — withholding is a prepayment, not a tax — but it is avoidable by making sure your exchange has your correct, certified tax ID before the year turns.
Bitcoin Is 41% Below Its Peak — the Tax-Loss Harvest Window Closes December 31
Here is the one part of the 2027 tax story that can save you money instead of costing it. Bitcoin traded at about $73,700 on November 11, 2026, down 41% from its all-time high of $126,080, with the Fear & Greed Index at 29 — firmly in fear territory. Ethereum sat near $2,053, and US spot Bitcoin ETFs lost $1.28 billion in the week of November 2–6, their largest weekly outflow since late June. Millions of holders who bought in 2025 and 2026 are sitting on unrealized losses. A loss only helps your tax bill if you realize it — sell the asset — before December 31, 2026. Sell on January 2 and the loss belongs to tax year 2027, a full year later.
Capital losses offset capital gains first, and in the US up to $3,000 of net capital losses can offset ordinary income each year, with the rest carried forward. That makes a down year the best year to clean up a portfolio: sell the losers, bank the losses, and use them against gains you already realized earlier in 2026. And crypto still has one structural advantage over stocks: as things stand, the wash-sale rule that blocks loss claims when you repurchase a stock within 30 days does not apply to crypto. You can sell a losing position and buy it back without waiting 30 days and still claim the loss — a window lawmakers have repeatedly tried to close. If you are new to Bitcoin itself, start with our guide to what Bitcoin is and how BTC works before making any moves.
The timing matters twice over. First, the 2026 tax year ends in seven weeks. Second, any coin you buy from now on and hold on the same exchange becomes a "covered" asset whose basis your broker will track. Harvesting losses in a down market is the single highest-value tax move most holders can make this year, and it expires at midnight on December 31.
What Most People Get Wrong About Crypto Tax in 2027
Myth one: "If I never cash out to dollars, I owe nothing." Wrong. In the US and most other countries, swapping one crypto for another is a taxable disposal. Trading Bitcoin for Ethereum, or selling a token for a stablecoin, realizes a gain or loss at that moment — the dollars never have to touch your bank account.
Myth two: "My exchange reports my gains, so I don't need records." Wrong in the other direction. Your exchange reports proceeds, and from 2027 basis only for covered assets. For anything transferred in, bought before 2026, or traded on a DEX, your broker reports nothing about your cost — and the IRS expects your return to fill the gap.
Myth three: "DeFi isn't reported, so it isn't taxed." The reporting exemption for DeFi protocols is not a tax exemption. The income is taxable; only the automatic form is missing. That actually increases your audit risk, because the gap between what exchanges report and what you declare gets wider.
Myth four: "A 1099-DA with a big number means I owe tax on that number." The form shows gross proceeds, not profit. A $100,000 proceeds figure on coins you bought for $98,000 is a $2,000 gain. Failing to file Form 8949 with your basis is how people get CP2000 letters demanding tax on the full $100,000.
Myth five: "Crypto tax only matters in the US." The 47 jurisdictions exchanging CARF data in 2027, the EU's DAC8, the UK's CARF rollout and Japan's tax reform — a bill cutting crypto gains tax passed the lower house in 2026 — show this is now a global reporting regime. Moving exchanges does not move you out of it.
5 Moves to Make Before December 31, 2026
Do these five things before the year ends:
- Harvest your losses now. Identify every position sitting below its cost basis, sell the losers before December 31, and bank the losses against 2026 gains. Check the wash-sale position with a tax professional first — the window is open today, but rules change.
- Export every transaction history. Pull complete histories from every exchange, wallet and DeFi protocol you used in 2025 and 2026, and reconcile them in one place while the data is still available. Exchanges close accounts and APIs change; your records should not depend on them.
- Fix your cost-basis method. Decide how you identify sold lots — and tell each broker your instruction before you sell anything else. From 2027, a missing instruction means the broker's default applies.
- Verify your tax ID everywhere. Make sure every exchange and broker has your correct, certified taxpayer identification number, or you risk 24% backup withholding on 2027 sales in the US and frozen withdrawals under DAC8 in Europe.
- Reconcile your first 1099-DA. Compare the form you received in early 2026 against your own records now, while there is time to correct it. If the basis or acquisition date is wrong, you will need your own documentation ready when the 2027 form arrives with basis included.
What Happens Next in 2027: 3 Scenarios
Base case — messy but manageable. The first basis-inclusive 1099-DAs arrive in February 2027, CP2000 notices spike as automated matching compares broker basis against taxpayer returns, and most holders who kept records sort it out with corrected figures on Form 8949. DAC8 and CARF exchanges begin on schedule, and the biggest practical change is that underreporting becomes much harder to sustain.
Bull case for holders — clarity arrives. Congress or the Treasury issues guidance smoothing the rough edges — for example, a de minimis exemption for small transactions — and Japan's tax cut, already through the lower house, becomes law and pressures other countries to compete on rates.
Bear case — the crackdown scenario. Mismatches trigger a wave of enforcement, the wash-sale loophole for crypto gets closed in a year-end bill, and stablecoin reporting under the GENIUS Act adds a new layer of forms for everyday stablecoin use. Holders who treated 2026 as a grace period discover it was actually the last quiet year.
Whichever scenario plays out, the direction is the same: crypto tax in 2027 is a data-matching regime, not an honor system. The people who do best are not the ones with the cleverest structures — they are the ones with complete records, a chosen basis method, and losses harvested before the deadline. If you are planning your first purchase in this new environment, read our guide to how to buy Bitcoin in the USA in 2026 before you send a dollar.
FAQs: Crypto Tax in 2027
Do I have to pay tax on crypto I haven't sold?
No. In the US and most countries, simply holding crypto is not taxable. Tax is triggered when you dispose of it — by selling, swapping it for another crypto, or spending it. Staking rewards and airdrops are generally taxable as income when you receive them.
What is Form 1099-DA and when will I get it?
It is the IRS form brokers use to report your digital-asset sales. The first forms, covering 2025 sales, were sent in early 2026. Forms covering 2026 sales arrive by February 15, 2027, and for the first time they will include cost basis for "covered" assets bought on or after January 1, 2026 and kept on the same exchange.
What if the cost basis on my 1099-DA is wrong?
Report your correct basis and acquisition date on Form 8949 with your own documentation. The IRS regulations say you are not required to use a transfer-in date shown on the form as your acquisition date. Keep exchange statements, wallet exports and purchase receipts to support your numbers.
Does crypto tax reporting apply outside the US?
Yes. The EU's DAC8 and the UK's CARF rules both apply from January 1, 2026, with first reports and data exchanges in 2027. Forty-seven jurisdictions are targeting first CARF exchanges in 2027. Your exchange may already be collecting your tax identification number for this purpose.
Can I still harvest tax losses in a down market?
Yes, if you sell before December 31, 2026 the loss counts for tax year 2026. Losses offset gains first, and up to $3,000 of net losses can offset ordinary income per year in the US, with the rest carried forward. As things stand, crypto is not covered by the stock wash-sale rule, so repurchasing quickly does not automatically kill the loss — but confirm the current position with a tax professional.
Are DeFi trades reported to the IRS?
Not automatically. Congress repealed the rule that would have required DeFi protocols and DEXs to file 1099-DAs, so no form arrives for those trades. The gains are still taxable, and your own records are the only evidence you have.
Conclusion: 2027 Is the Year the Taxman Gets the Data
Crypto spent a decade as the asset class the tax system could not see. That era ends in 2027. The IRS will have your cost basis for covered assets, 47 countries will be swapping transaction data, UK and EU providers will file their first reports, and a missing tax ID can cost you 24% of a sale before you file anything. None of that is a reason to stop holding crypto — but it is a reason to stop winging the paperwork. Harvest your losses before December 31, export your histories, fix your basis method, verify your tax ID, and reconcile the form you already received.
This article is for information only and is not tax, legal or financial advice. Tax rules change frequently and differ by country and personal circumstances — consult a qualified tax professional before making decisions based on this article.